
An insurance adjuster’s total loss offer isn’t a final verdict; it’s the opening move in a high-stakes negotiation. If you’ve recently stared at a settlement check that barely covers a down payment on a replacement vehicle, you know the frustration of being undervalued. You’re likely wondering, what are my options if my car is totaled under New York’s strict 2026 regulations? It’s a chaotic situation, but you don’t have to accept a lowball figure just because an algorithm says so.
We’ll show you how to navigate the 75 percent threshold and maximize your payout by including the mandatory 8.875 percent NYC sales tax. This guide breaks down your right to keep the vehicle through salvage retention and explains how the recent repeal of the 90/180-day rule changes your path to a personal injury claim. You’ll learn to use the 35-day right of recourse to force insurers back to the table. From challenging condition deductions to identifying if your totaled car is evidence of a deeper injury case, we provide the shield you need against aggressive adjusters who prioritize their bottom line over your recovery.
Key Takeaways
- Understand the New York 75% rule to determine if your vehicle qualifies as a total loss under state insurance guidelines.
- Ensure your settlement includes the mandatory 8.875% NYC sales tax, which insurers often omit from initial lowball offers.
- Evaluate what are my options if my car is totaled, specifically choosing between a full cash settlement or retaining the vehicle through the DMV salvage process.
- Identify how a total loss serves as critical evidence for a personal injury claim, especially under New York’s new 2026 medical threshold requirements.
- Learn how to challenge insurance valuations using local market data and professional legal advocacy to secure a fair replacement value.
Understanding the Total Loss Threshold in New York
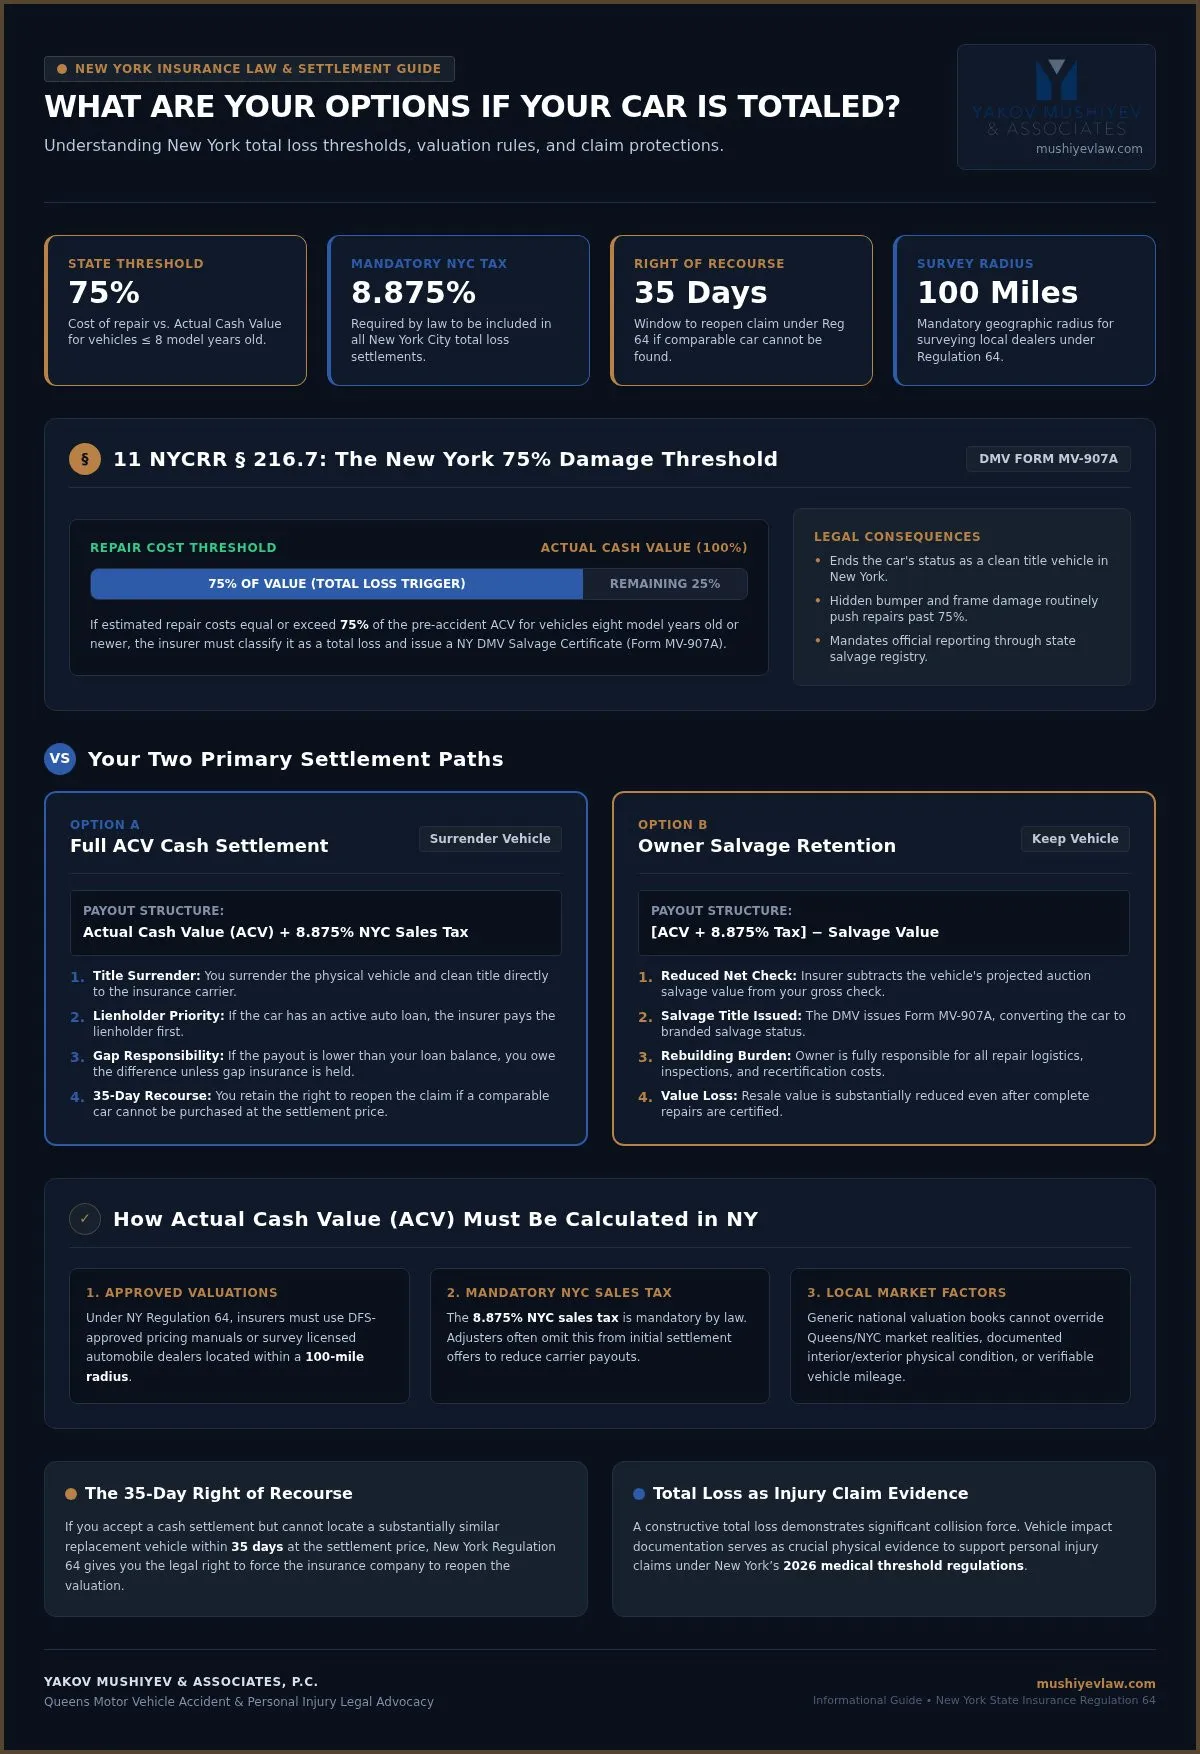
New York doesn’t leave the definition of a totaled car to chance or insurance company whim. Under state law, specifically 11 NYCRR § 216.7, a vehicle is classified as a total loss when the cost of repairs exceeds a specific percentage of its value. For many drivers, this realization is devastating. You aren’t just losing a machine; you’re losing your primary means of transportation in a borough like Queens where timing is everything. When an adjuster declares a constructive total loss, they’re essentially saying the math of fixing the car no longer makes sense for their bottom line.
To better understand this concept, watch this helpful video:
If you’re asking, “what are my options if my car is totaled,” the first step is understanding that the insurance company’s initial figure isn’t set in stone. They rely on adjusters who use specialized software to minimize payouts. These adjusters aren’t your friends. They’re representatives of a corporation looking to settle for the lowest possible amount. They often overlook the local market realities of the five boroughs to save a few dollars.
How New York Calculates Actual Cash Value
Actual Cash Value (ACV) is the fair market value of your vehicle immediately before the crash occurred. Unlike replacement cost, which pays for a brand-new version of your car, ACV accounts for depreciation. In Queens, adjusters look at local market demand, mileage, and the physical condition of the interior and exterior. Under Regulation 64, insurers must use approved methods like averaging DFS-approved manuals or surveying local dealers within 100 miles. Don’t let them tell you a generic Blue Book value is the final word; the specific condition and location of your vehicle matter. Crucially, your settlement must include the 8.875 percent NYC sales tax, as required by law.
The 75% Damage Threshold Explained
New York follows a strict 75 percent threshold for vehicles eight model years old or newer. If the estimated repair costs reach 75 percent of the vehicle’s pre-accident ACV, the insurer must classify it as a total loss. Hidden damage often lurks beneath the bumper or within the frame, quickly pushing a seemingly minor repair over this legal limit. Once this threshold is crossed, the New York DMV requires the issuance of a Salvage Certificate (Form MV-907A). This document effectively ends the car’s life as a clean title vehicle. Knowing what are my options if my car is totaled starts with verifying their math against these state-mandated limits before you sign any paperwork.
Your Two Primary Settlement Options: ACV vs. Retention
Once the dust settles after a collision, you’re forced to make a high-stakes financial decision. When considering what are my options if my car is totaled, you generally have two paths: walking away with a check or keeping the wreckage to attempt a rebuild. Neither choice is simple, and the wrong move can leave you thousands of dollars short of what you need to get back on the road. Insurance adjusters often push for the easiest resolution for their company, not the one that protects your interests.
Accepting the Cash Settlement
Most New York drivers choose to surrender the vehicle in exchange for the Actual Cash Value (ACV). If you select this route, the insurer takes the car and the title, and you receive a payout based on the car’s pre-accident market value. Under New York law, this settlement must include the 8.875 percent NYC sales tax. If you still have an active loan, the insurance company will pay the lienholder first. If the payout is less than your remaining balance, you’ll be responsible for the “gap” unless you have a specific gap insurance policy. Under Regulation 64, you have a 35-day right of recourse if you cannot find a comparable vehicle at the offered price, allowing you to force the insurer to reopen the claim. Before signing any release, it is wise to consult a motor vehicle accident attorney to ensure you aren’t leaving money on the table.
Keeping Your Totaled Vehicle (Owner Retention)
If you choose “Owner Retention,” you keep the car, but your payout is significantly reduced. The insurer calculates your net check by taking the full ACV plus sales tax and then subtracting the “salvage value,” which is the amount they would have received at a salvage auction. While this may seem appealing for a car with sentimental value, the administrative burden is immense. You must navigate the following hurdles:
- The Salvage Certificate: You’ll receive an MV-907A, which prevents the car from being driven legally until it’s “rebuilt.”
- The DMV Inspection: You must pay a $200 filing fee and submit the car to a rigorous physical examination by the DMV Auto Theft Unit, often at the Queens Village inspection site.
- Insurance Barriers: Many carriers refuse to provide comprehensive or collision coverage for a vehicle with a rebuilt salvage title, leaving you vulnerable to future losses.
Most Queens mechanics warn that structurally totaled cars never drive the same way again. Understanding what are my options if my car is totaled means recognizing that keeping the car often turns into a costly, time-consuming secondary crisis.
How to Challenge a Lowball Insurance Valuation
The first offer you receive from an insurance company is rarely their best offer. It is a calculated opening move in a negotiation designed to save the carrier money at your expense. Insurers frequently use automated software like CCC ONE or Mitchell to generate reports that systematically dock value for vague “condition deductions” or “dealer prep” costs. These algorithms often ignore the premium prices commanded by vehicles in the high-demand Queens and Long Island markets. When you ask what are my options if my car is totaled, you must realize that negotiation is your most powerful tool for securing a fair settlement.
You don’t have to accept a clinical, computer-generated number that doesn’t reflect reality. If the offer feels low, it’s because the adjuster is likely cherry-picking the cheapest comparable vehicles from distant counties rather than looking at what it actually costs to buy a car in the five boroughs. You have the right to push back with your own evidence. Advocacy starts with refusing to be intimidated by a billion-dollar corporation’s math.
Building Your Valuation Dossier
To win a valuation dispute, you must present a professional dossier that proves your vehicle’s worth. Start by gathering local listings for the exact same year, make, model, and trim level from dealerships within a 100-mile radius. Focus on Queens and Long Island retailers to reflect local market pricing. You are entitled to a comparable vehicle, not just the lowest price found online. Additionally, compile receipts for any recent upgrades or significant maintenance performed in the last 12 months. New tires, recent brake work, or engine repairs can add hundreds of dollars back into your Actual Cash Value. Maintenance records serve as definitive proof that your car was in “above average” condition before the wreck.
Invoking the Appraisal Clause
If negotiations reach a deadlock, you have a hidden weapon in your insurance policy known as the Appraisal Clause. Under New York Regulation 35-D, this clause allows you to hire an independent certified appraiser to provide a third-party valuation. The insurance company then hires their own, and if the two cannot agree, an “umpire” makes a final, binding decision. While you must pay for your own appraiser, this strategy often pays for itself when dealing with high-value, classic, or heavily customized vehicles. It bypasses the adjuster’s scripted denials and forces a professional, evidence-based resolution. Understanding what are my options if my car is totaled means knowing when to stop talking to an adjuster and start using the legal mechanisms built into your policy to protect your financial recovery.
When a Totaled Car Signals a Serious Personal Injury Claim
A crumpled frame and deployed airbags are not just insurance line items. They are “Exhibit A” in a court of law. When you’re evaluating what are my options if my car is totaled, you must recognize that the violent kinetic energy required to reach New York’s 75 percent damage threshold doesn’t stop at the vehicle’s exterior. It transfers directly to the occupants. Insurance companies want you to believe that property damage and personal injury exist in separate silos. This is a strategic lie designed to minimize their liability. Never settle your property claim until you speak with a car accident lawyer Jamaica Avenue. Our firm understands that a totaled car is often the first indicator of a life-altering injury.
Connecting Vehicle Crush to Bodily Injury
Total loss accidents usually involve high-velocity impacts that cause the cabin to deform or the frame to buckle. These forces lead to significant medical conditions that aren’t always immediately apparent. Common traumas include traumatic brain injuries (TBI) from rapid deceleration, internal organ damage, and complex spinal fractures. Adjusters often use a “low impact” defense to deny injury claims, but a totaled vehicle provides prima facie evidence that the collision was severe. You need a medical evaluation immediately. Objective imaging like MRIs and CT scans are now critical under the May 2026 New York law changes, which eliminated the 90/180-day disability category. You can no longer rely on temporary incapacity to prove your case; you need objective proof of a serious injury.
Protecting Your Right to Sue
The insurance company is likely pressuring you to sign a “Full and Final Release” for your property damage claim. You must be extremely careful. These documents often contain hidden language that waives your right to pursue a personal injury lawsuit later. They want to close the file before you realize your persistent neck pain is actually a herniated disc. Under New York’s 2026 shift to a modified comparative fault rule, you’re barred from recovery if you’re found more than 51 percent at fault. Adjusters will use the property damage file to shift blame onto you. To protect your future, consult a Personal Injury Lawyer in Rosedale, Queens before putting pen to paper.
Navigating the aftermath of a wreck requires a shield against predatory adjusters who prioritize their bottom line over your health. If you are asking what are my options if my car is totaled, remember that the car can be replaced, but your right to medical compensation is finite. If you’re unsure about the fine print in your settlement offer, contact us for a professional case assessment. We handle the legal heavy lifting so you can focus on your recovery.
Why a Queens Accident Attorney is Your Best Defense
Facing an insurance giant alone is a losing game. When you’re forced to ask what are my options if my car is totaled, you are up against adjusters who view your trauma as a math problem. We serve as your necessary shield against these formidable opponents. Our firm manages all communications with adjusters, ensuring you don’t make a recorded mistake that could jeopardize your financial recovery. We identify every available insurance pocket, including Underinsured Motorist (UIM) and excess liability coverage, to maximize your total settlement. Advocacy isn’t just about the car; it’s about the restoration of your life.
The Yakov Mushiyev & Associates, P.C. promise is one of relentless advocacy for victims in Rosedale, Rochdale, and throughout Queens. We understand the “bigger picture” where a totaled car often indicates significant physical trauma. By handling the legal heavy lifting, we allow you to focus on your medical recovery while we prepare to fight for every dollar you deserve. We refuse to settle for anything less than what is fair and just under New York’s complex 2026 insurance landscape.
The Benefit of a Local Queens Advocate
Regional expertise matters in a complex jurisdiction like New York City. We possess deep knowledge of local courts and the specific traffic laws governing high-volume thoroughfares like the Van Wyck and Belt Parkway. Our firm provides personalized attention to victims in the Jamaica Avenue, Rosedale, and Rochdale areas. We don’t just look at the car; we use accident reconstruction experts to prove liability under the new 2026 modified comparative fault rules. If the insurance company tries to shift 51 percent of the blame onto you to bar your recovery, we fight back with objective data to protect your claim. Our street-smart approach ensures no detail of the local Queens market is ignored.
Getting Started with a Risk-Free Consultation
Time is of the essence after a devastating wreck. To begin your journey toward justice, you should gather your police reports, scene photos, and any initial repair estimates. When you’re weighing what are my options if my car is totaled, our team provides the clinical precision needed to evaluate the true value of your case. We operate on a risk-free, contingency basis. This means we only get paid if we win your case, reinforcing our commitment to a client-first philosophy. This arrangement removes the financial barrier to high-stakes legal representation, allowing you to challenge powerful entities without upfront costs.
Don’t settle for a figure that ignores your physical pain and future needs. Contact Yakov Mushiyev & Associates, P.C. today for a complimentary initial assessment of your total loss and personal injury case. We are the tireless advocates you need to navigate this managed journey toward full restoration. Our doors are open to the community as a steady, calm, and approachable guide through your state of crisis.
Secure Your Future After a Total Loss
You shouldn’t have to fight a billion-dollar insurance company while recovering from a traumatic crash. Understanding what are my options if my car is totaled is the first step in reclaiming your financial stability. Whether you accept the Actual Cash Value or pursue salvage retention, you must ensure the insurer includes the mandatory 8.875 percent NYC sales tax and reflects the true local market value. A totaled vehicle serves as powerful evidence of the physical forces that caused your injuries, which is critical under New York’s strict 2026 medical threshold requirements.
Yakov Mushiyev & Associates, P.C. provides the shield you need against aggressive adjusters. With over 20 years of experience in NY personal injury law, we are fierce advocates against insurance company lowball tactics. We work on a contingency fee basis; you pay nothing unless we win your case. You don’t have to navigate this journey alone. Take the decisive step toward justice and restoration today.
Get a Free Case Evaluation from a Queens Car Accident Lawyer and let us secure the settlement you deserve. Your recovery is our priority.
Frequently Asked Questions
How long does an insurance company have to pay for a totaled car in NY?
New York law requires insurers to settle claims promptly, typically within 30 days of receiving a completed proof of loss. If the insurer delays beyond this timeframe, they may be subject to regulatory scrutiny under Regulation 64. For Rosedale residents, it’s vital to maintain a detailed timeline of all communications. We ensure adjusters don’t use delay tactics as a weapon to force you into a lower settlement while you’re vulnerable without transportation.
Can I negotiate the settlement for my totaled car?
You absolutely can negotiate the initial offer. Adjusters often use algorithms that ignore the high market demand in Queens and Rochdale. If the offer is too low, you can invoke the appraisal clause or gather local dealership comparables. Understanding what are my options if my car is totaled includes using your 35-day right of recourse under New York law to challenge a settlement that doesn’t cover the cost of a replacement vehicle.
What happens if I still owe money on my totaled car loan?
The insurance settlement is paid directly to your lienholder first. If the Actual Cash Value is lower than your loan balance, you’re responsible for the difference. This “gap” can be devastating without specific gap insurance coverage. Our firm reviews your policy to identify every potential source of recovery, ensuring that a totaled vehicle doesn’t leave you with a massive debt for a car you can no longer drive on Queens streets.
Do I have to pay my deductible if my car is totaled and it wasn’t my fault?
If you file through your own collision coverage, you must pay the deductible upfront. Your insurer will then attempt to recover that amount from the at-fault driver’s carrier through subrogation. If you file a third-party claim against the negligent driver’s policy, no deductible applies. We fight to hold the responsible party accountable so you aren’t forced to pay out of pocket for a wreck that wasn’t your fault in Rochdale.
What is the “75% rule” for totaled cars in New York?
New York strictly enforces a 75 percent threshold for vehicles eight model years old or newer. If the estimated repair costs exceed 75 percent of the car’s pre-accident market value, it must be declared a total loss. This rule protects consumers from driving structurally compromised vehicles. We verify the insurer’s math to ensure they aren’t manipulating repair estimates to avoid paying the full value you’re entitled to under state regulations.
Can I keep my totaled car and fix it myself in Queens?
You can keep the vehicle through “owner retention,” but the salvage value is deducted from your check. In Queens, you’ll then need to navigate a rigorous DMV theft-examination process at the Queens Village inspection site to secure a rebuilt salvage title. Most local mechanics advise against this because structural integrity is rarely fully restored. We help you weigh the financial burden of retention versus accepting a full cash settlement for your recovery.
Does a totaled car automatically mean I have a personal injury case?
A totaled car is powerful evidence of significant kinetic force, but it doesn’t automatically create a personal injury case. Under the May 2026 law changes, you must prove a “serious injury” using objective medical imaging like MRIs or EMG studies. When asking what are my options if my car is totaled, you should also consider the physical trauma often hidden behind property damage. We use the vehicle’s crush data to link collision forces to your injuries.
What if the other driver doesn’t have enough insurance to cover my totaled car?
New York’s minimum property damage liability is only $10,000, which is often insufficient for modern vehicles. If the at-fault driver is underinsured, you may need to rely on your own collision coverage or Supplementary Uninsured/Underinsured Motorist (SUM) policy. We relentlessly pursue every available insurance pocket to ensure you aren’t left footing the bill for someone else’s negligence on the busy streets of Rosedale or Rochdale. Our advocacy ensures your rights remain protected.