
The fastest check you receive from an insurance company is often the most expensive mistake you’ll ever make. In the chaotic days following a crash, an adjuster might offer a payout that covers your current bills, but it rarely accounts for the long term. You’re likely facing the dangers of accepting a fast settlement offer before you even know the full extent of your injuries. We understand the pressure of mounting medical bills and the stress of lost wages from missing work in NYC. It’s natural to want a resolution, but speed is the insurance company’s greatest weapon against you.
This guide explains why these corporations rush the process and how a quick payout can permanently strip you of your rights to full compensation. You’ll learn how to calculate the true value of your claim, avoid a legal mistake you cannot undo, and ensure you secure enough money for your future medical needs. Protecting your recovery starts with knowing when to say no to a lowball offer and how to hold negligent parties accountable for the full scope of your trauma.
Key Takeaways
- Understand why insurance adjusters rush to close files for the lowest possible amount before you realize the true extent of your injuries.
- Recognize the dangers of accepting a fast settlement offer, specifically how signing a “Release of All Claims” permanently strips you of your right to future compensation.
- Learn how to calculate the full value of your claim by accounting for future lost earning capacity and non-economic damages like pain and suffering.
- Discover the essential rules for handling an adjuster’s first call, including why you shouldn’t discuss your treatment or provide recorded statements alone.
What Is a Fast Settlement Offer and Why Is the Insurance Company Rushing You?
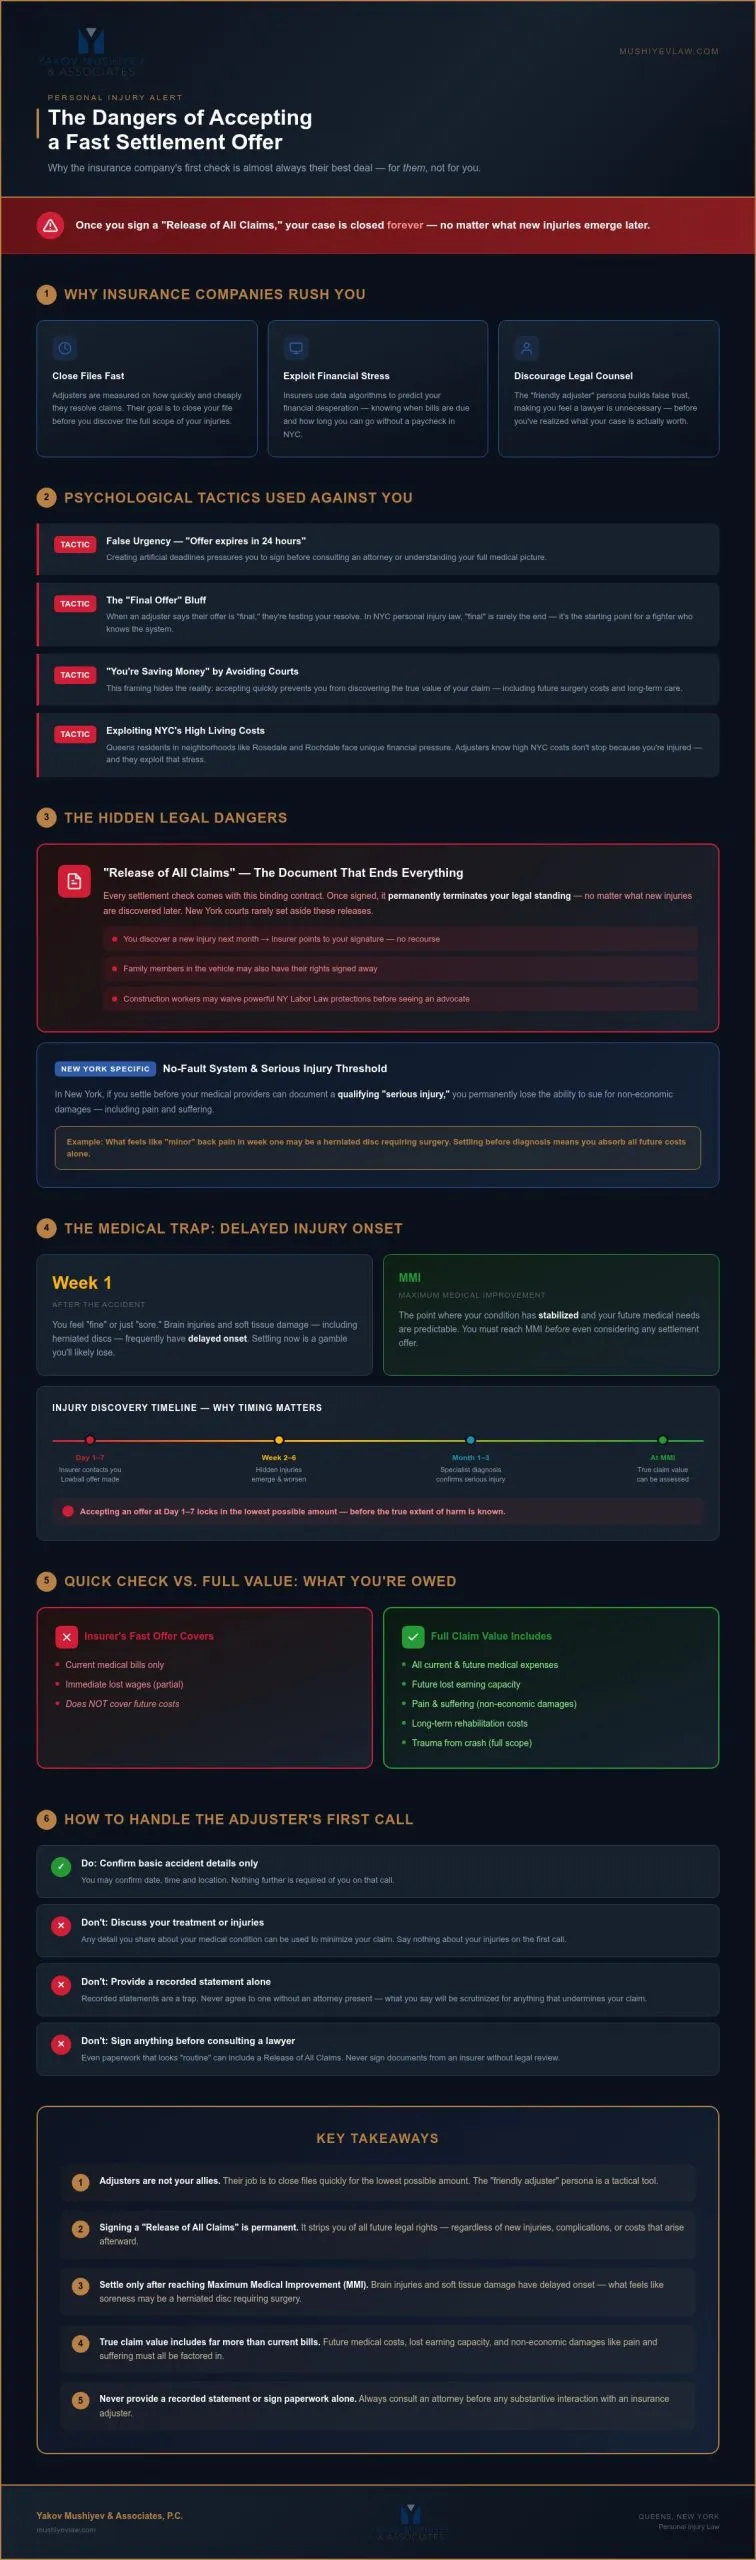
A fast settlement offer is a lump-sum payment proposed by an insurance company within days or weeks of your accident. On the surface, it looks like a lifeline. In reality, it’s a calculated strike. Insurance adjusters aren’t there to help you recover; they’re there to close files quickly and for the lowest possible amount. If an adjuster is rushing you to sign paperwork before you’ve even seen a specialist, it’s a massive red flag. They know that once you understand the true value of your claim, the price tag for your recovery will skyrocket. One of the primary dangers of accepting a fast settlement offer is the immediate loss of all future legal leverage.
The “friendly adjuster” is a specific persona designed to discourage you from seeking legal counsel. They might call you shortly after your construction accident or car crash, sounding empathetic and helpful. Don’t be fooled. This friendliness is a tactical tool used to build a false sense of trust, making you feel like a lawyer is unnecessary. They want to resolve the case before your medical bills start piling up and before you realize the full extent of your trauma.
The Economics of the Lowball Offer
Insurance companies rely on sophisticated data algorithms to predict your financial desperation. They know when bills are due and how long a Queens resident can typically go without a paycheck. These corporations often engage in aggressive insurance bad faith practices by pressuring victims to accept pennies on the dollar. A lowball offer is a strategic financial move to minimize corporate liability. When an adjuster tells you their offer is “final,” they’re usually testing your resolve. In the high-stakes world of NYC personal injury law, “final” is rarely the end of the conversation. It’s simply the starting point for a fighter who knows the system.
Psychological Tactics Used on Queens Accident Victims
Residents in neighborhoods like Rosedale and Rochdale often face a unique set of pressures. High NYC living costs don’t stop just because you’re injured. Adjusters exploit this stress by creating a false sense of urgency. They’ll claim the offer is only available for 24 hours or that you’re “saving money” by avoiding the courts. It’s a trap. Another of the dangers of accepting a fast settlement offer is that it prevents you from ever discovering what your case is actually worth. They want you to settle before you realize that your “minor” back pain is actually a herniated disc requiring surgery. We act as your shield, neutralizing these tactics so you can focus on healing.
The Hidden Dangers of Accepting a Quick Payout
Accepting a check today often means forfeiting your rights tomorrow. In New York, the legal landscape is particularly treacherous due to the No-Fault insurance system and the “serious injury threshold.” If you settle before your medical providers can document a qualifying serious injury, you lose the ability to sue for non-economic damages like pain and suffering. This is a catastrophic loss for victims of car accidents or construction site falls. The dangers of accepting a fast settlement offer extend far beyond the immediate dollar amount; they threaten your ability to survive the long-term fallout of a crash. For those working on job sites in Queens, a quick signature can waive powerful protections under New York Labor Laws before you’ve even spoken to an advocate.
The Finality of the Legal Release
Every settlement check is accompanied by a document titled “Release of All Claims.” This isn’t just administrative paperwork; it’s a binding contract that terminates your legal standing. Once that ink is dry, your case is closed forever. New York courts rarely set aside these releases based on a claimant’s misunderstanding of the terms. If you discover a new injury next month, the insurance company will simply point to your signature. You might even be inadvertently signing away the rights of family members who were in the vehicle with you. Knowing your rights as an insurance claimant is essential to prevent being bullied into a permanent legal trap that leaves you with no recourse.
The Trap of Unforeseen Medical Complications
Medical science proves that trauma often hides. Brain injuries and soft tissue damage, such as herniated discs, frequently have a delayed onset. You might feel “fine” or just “sore” in the first week. Settling during this window is a gamble you’ll likely lose. You must reach Maximum Medical Improvement (MMI) before even considering an offer. MMI is the point where your condition has stabilized and your future medical needs are predictable. Without this medical clarity, a small payout today will leave you drowning in debt when complications arise. Consider the math of a typical lowball offer. An adjuster might offer $7,500 to cover your current ER visit and a few weeks of missed work. If you later discover you need surgery or physical therapy for a year, that money evaporates in weeks. A Queens personal injury attorney can help you navigate these medical timelines to ensure your compensation matches your actual needs.
Quick Check vs. Full Value: Calculating Your True Losses
A fast check is a snapshot of your current crisis. A full settlement is a projection of your future needs. Insurance adjusters focus on immediate bills to distract you from the dangers of accepting a fast settlement offer, which often ignores your long-term earning capacity. New York’s “Collateral Source” rule adds another layer of complexity. This rule generally prevents a defendant from reducing their liability just because you have health insurance or other benefits. Adjusters won’t explain this. They want you to believe their offer is the maximum possible, when it’s often just the minimum they think you’ll accept. Only a seasoned advocate can uncover the “invisible” costs of your accident, such as the psychological trauma and the permanent loss of career momentum.
Quantifying non-economic damages like pain, suffering, and loss of enjoyment of life requires a deep understanding of the Queens legal landscape. In a major metropolitan area, an injury doesn’t just stop you from working. It stops you from navigating the city, caring for your family, and living with dignity. We don’t let insurance companies treat your life like a line item on a spreadsheet. Your recovery must reflect the total impact of the negligence you’ve endured.
Long-Term Financial Impact Analysis
NYC inflation is a silent predator for accident victims. Healthcare costs in Queens rise faster than standard inflation, meaning a payout that feels sufficient today will likely fail you in five years. We account for every detail. This includes necessary home modifications for a construction accident survivor or decades of specialized physical therapy. If your injury forces you off your professional path, we don’t just look at current lost wages. We calculate the true cost of your missed career trajectory and lost retirement contributions. A quick payout never accounts for the compound interest of a lost career.
The Role of Liability and Comparative Negligence
New York follows a pure comparative negligence rule. This means your compensation is reduced by your percentage of fault. Insurance adjusters use this as a weapon. They’ll claim you were partially responsible for the slip and fall or truck crash to justify a “take it or leave it” fast offer. They want you to feel lucky to get anything at all. Understanding these tactics is vital when Navigating the NY Claim Process. We serve as your shield, refuting false claims of negligence to ensure your recovery reflects the defendant’s true liability. One of the greatest dangers of accepting a fast settlement offer is that it essentially validates the insurance company’s biased version of events before the evidence is even fully reviewed.
How to Handle the Insurance Adjuster’s First Call
The first call from an insurance adjuster is a strategic interrogation disguised as a courtesy check-in. Within hours of your accident, they’re already building a file to minimize your payout. You must treat this interaction with clinical precision. Their primary goal is to secure information they can use to devalue your claim before you understand the dangers of accepting a fast settlement offer. To protect your future, you must follow three absolute rules. First, never give a recorded statement without legal counsel present. Second, do not discuss the extent of your injuries until you’ve completed your medical treatment. Third, do not sign any documents, especially “standard” medical authorizations, without a professional review. These forms often grant insurers unlimited access to your entire medical history, allowing them to blame your current pain on unrelated past events.
Declining a fast offer doesn’t mean you’re being difficult; it means you’re being diligent. You can remain polite while maintaining your boundaries. If an adjuster pushes for a quick resolution, simply state that you’re focusing on your recovery and aren’t prepared to discuss financial figures yet. This keeps the door open for future negotiations while preventing you from locking yourself into an inadequate sum.
Protecting Your Words
The most dangerous phrase you can utter to an adjuster is “I’m fine.” In the polite context of a phone call, it’s a common reflex. In a legal context, it’s an admission that your injuries aren’t serious. Adjusters use these “friendly check-ins” to catch you off guard when you’re vulnerable or medicated. Use this specific script to end the conversation: “I am not prepared to discuss a settlement until my medical treatment is complete.” This statement is a definitive shield. It signals that you’re aware of the dangers of accepting a fast settlement offer and that you won’t be pressured into a premature decision.
When to Cease Direct Communication
Communication should stop immediately if an adjuster becomes aggressive, coercive, or starts blaming you for the accident. Signs of bad faith include threatening to withdraw an offer if you don’t sign today or implying that you don’t need a lawyer. Hiring Queens Injury Advocates Who Fight for You instantly terminates this harassment. Once you have representation, the insurance company is legally barred from contacting you directly. All calls, emails, and pressure tactics must go through your attorney. This transition allows you to focus on healing while a relentless fighter handles the corporate giants. If you’re feeling overwhelmed by persistent adjusters, contact our firm for a risk-free assessment to take back control of your case.
Why a Relentless Advocate Is Your Best Shield Against Lowball Offers
Billion-dollar insurance companies aren’t just corporations; they’re formidable opponents with endless resources. They use these resources to protect their bottom line, not your health. Yakov Mushiyev & Associates, P.C. acts as the necessary shield between you and these predatory entities. We level the playing field by providing the clinical precision of legal expertise combined with an aggressive advocacy style. One of the primary dangers of accepting a fast settlement offer is that it assumes you have no power to fight back. We prove that assumption wrong. Our firm is built on a “No Win, No Fee” promise, ensuring that financial status never prevents a Queens resident from securing top-tier representation. You can afford a street-smart fighter today because our interests are perfectly aligned with your recovery.
Our reputation for litigation is your greatest asset during negotiations. Insurance adjusters know which firms settle quickly and which firms are prepared to go to trial. When we demand full value, they listen because they know we have the experience to back it up. We don’t just accept the numbers the insurance company provides. We investigate the accident scene, gather expert testimony, and build a case that reflects the true scope of your trauma. This relentless approach forces insurers to take your claim seriously from the very beginning.
Our Proven Approach to NY Injury Claims
We manage the chaos so you can focus on healing. Our team handles the complex paperwork, aggressive adjusters, and strict legal deadlines that define the New York legal system. We possess specific expertise in the local dynamics of neighborhoods like Rosedale and Rochdale. We understand how a construction accident on a local site or a crash on a busy Queens thoroughfare affects your life and your community. By providing Relentless Advocacy for Queens Victims, we ensure that no detail is overlooked in your pursuit of justice. We move with urgency and momentum because we know that your bills won’t wait.
Take Action Before the Clock Runs Out
Time is a critical factor in every personal injury case. New York law imposes a strict Statute of Limitations on car and construction accidents. If you wait too long, you lose your right to seek compensation forever. Preserving evidence at the scene is equally vital, especially in high-traffic areas of Queens where conditions change rapidly. Surveillance footage can be erased and witnesses can disappear. Acting quickly allows us to secure the proof needed to defeat the dangers of accepting a fast settlement offer. Don’t let an insurance company dictate the terms of your future. Contact Yakov Mushiyev for a Free Case Assessment today and put a tireless advocate in your corner.
Secure Your Future Before You Sign
You have the power to stop the clock and demand justice. The insurance company’s rush is a calculated attempt to minimize their liability at your expense. By prioritizing speed over medical clarity, you risk losing the compensation required for your long-term healing. Understanding the dangers of accepting a fast settlement offer is the first step toward a recovery that accounts for every future surgery, every therapy session, and every day of missed work in NYC. A quick payout is a permanent trap that cannot be undone once the ink is dry.
Our firm provides the protective shield you need against these powerful corporate entities. With deeply rooted expertise in Rosedale and Rochdale, we act as relentless advocates who are intimidating to opponents but remain steady, calm guides for you. We operate on risk-free financial arrangements, which means we only get paid if you win. Don’t let an adjuster’s urgency dictate your family’s financial future. Don’t settle for less than you deserve; get a FREE consultation with a Queens Injury Fighter today. Your journey toward restoration starts with a single, decisive action. We are ready to move forward with you.
Frequently Asked Questions
Is a settlement final once I sign the release form?
A settlement is almost always final once you sign the “Release of All Claims” form. This document serves as a binding contract that permanently terminates your right to seek additional compensation for the same incident. New York courts rarely overturn these agreements, even if your medical condition worsens later. This finality is one of the primary dangers of accepting a fast settlement offer, as it prevents you from recovering costs for injuries discovered after the case is closed.
Why is the insurance company offering me money so quickly?
Insurance companies offer quick payouts to minimize their financial liability before you realize the true value of your claim. They know that early in the process, you may be stressed by hospital bills and lost wages in Queens. By offering a lump sum immediately, they hope to close the file before you consult a lawyer or discover undiagnosed internal trauma. Speed is a tactic used to protect their profits, not your physical recovery.
What happens if I discover more injuries after I settle my case?
If you discover new injuries after settling, you generally cannot reopen your case or ask for more money. The legal release you signed bars all future claims related to that accident. This is why it’s critical to reach Maximum Medical Improvement before entering negotiations. Settling too soon leaves you personally responsible for all future medical costs, including surgeries or long-term physical therapy that may become necessary months down the line.
Do I have to pay a lawyer upfront to fight a settlement offer?
No, you don’t have to pay anything upfront at our firm. We operate on a contingency-fee basis, often called a “no win, no fee” arrangement. This means we only receive payment if we successfully secure a settlement or verdict for you. This risk-free financial structure allows Rosedale and Rochdale residents to access high-quality legal representation against powerful insurance entities without any out-of-pocket costs, ensuring that justice is available regardless of your current financial situation.
Can I still sue if the accident was partially my fault in NY?
Yes, you can still seek compensation even if you were partially at fault. New York follows a “pure comparative negligence” rule, which allows you to recover damages reduced by your percentage of responsibility. For example, if you are found 20% at fault for a slip and fall, you can still recover 80% of your total damages. Insurance adjusters often exaggerate your fault to pressure you into a low offer, making professional legal advocacy essential.
How long do I have to file a personal injury claim in New York?
In New York, the statute of limitations for most personal injury claims, including car and truck accidents, is three years from the date of the incident. However, claims against government entities or construction accidents involving specific labor law violations may have significantly shorter deadlines, sometimes as little as 90 days to file a notice of claim. Missing these deadlines will permanently bar you from seeking compensation, so it’s vital to act quickly after your accident.
Should I sign the medical authorization forms the insurance adjuster sent me?
You should never sign blanket medical authorization forms without a lawyer’s review. These documents often grant the insurance company unlimited access to your entire medical history, not just records related to your recent accident. They use this information to search for pre-existing conditions and argue that your current pain is unrelated to the crash. We protect your privacy by ensuring the insurer only receives the specific records necessary for your current claim.
What is the average settlement for a car accident in Queens?
There is no true “average” settlement because every case depends on unique factors like the severity of injuries, total medical bills, and lost earning capacity. A minor soft-tissue injury will result in a different payout than a catastrophic construction accident. Factors like New York’s serious injury threshold and insurance policy limits also play a role. We focus on the specific details of your life in Queens to avoid the dangers of accepting a fast settlement offer and demand a payout that reflects your actual losses.